cryptolab
Most crypto “signals” promise the price direction. cryptolab checks that with rigorous tests and says plainly when there is no edge.
What it computes
Market efficiency tests, volatility with GJR-GARCH and HAR-RV, market regimes with a hidden Markov model, the return distribution one day ahead and a walk-forward check against simple models.
An example on BTC
On 3,000 hourly BTC/USDT bars the probability of a rise over a day came out at 52%, and the tool says: no edge. GARCH forecasts volatility slightly better than simple models, but the Diebold–Mariano test does not find the difference significant.
A fast core
The heaviest computations, the GARCH likelihood and the Hurst exponent, are written in C++ and bound to Python. A dedicated test checks that C++ and Python give the same answer.
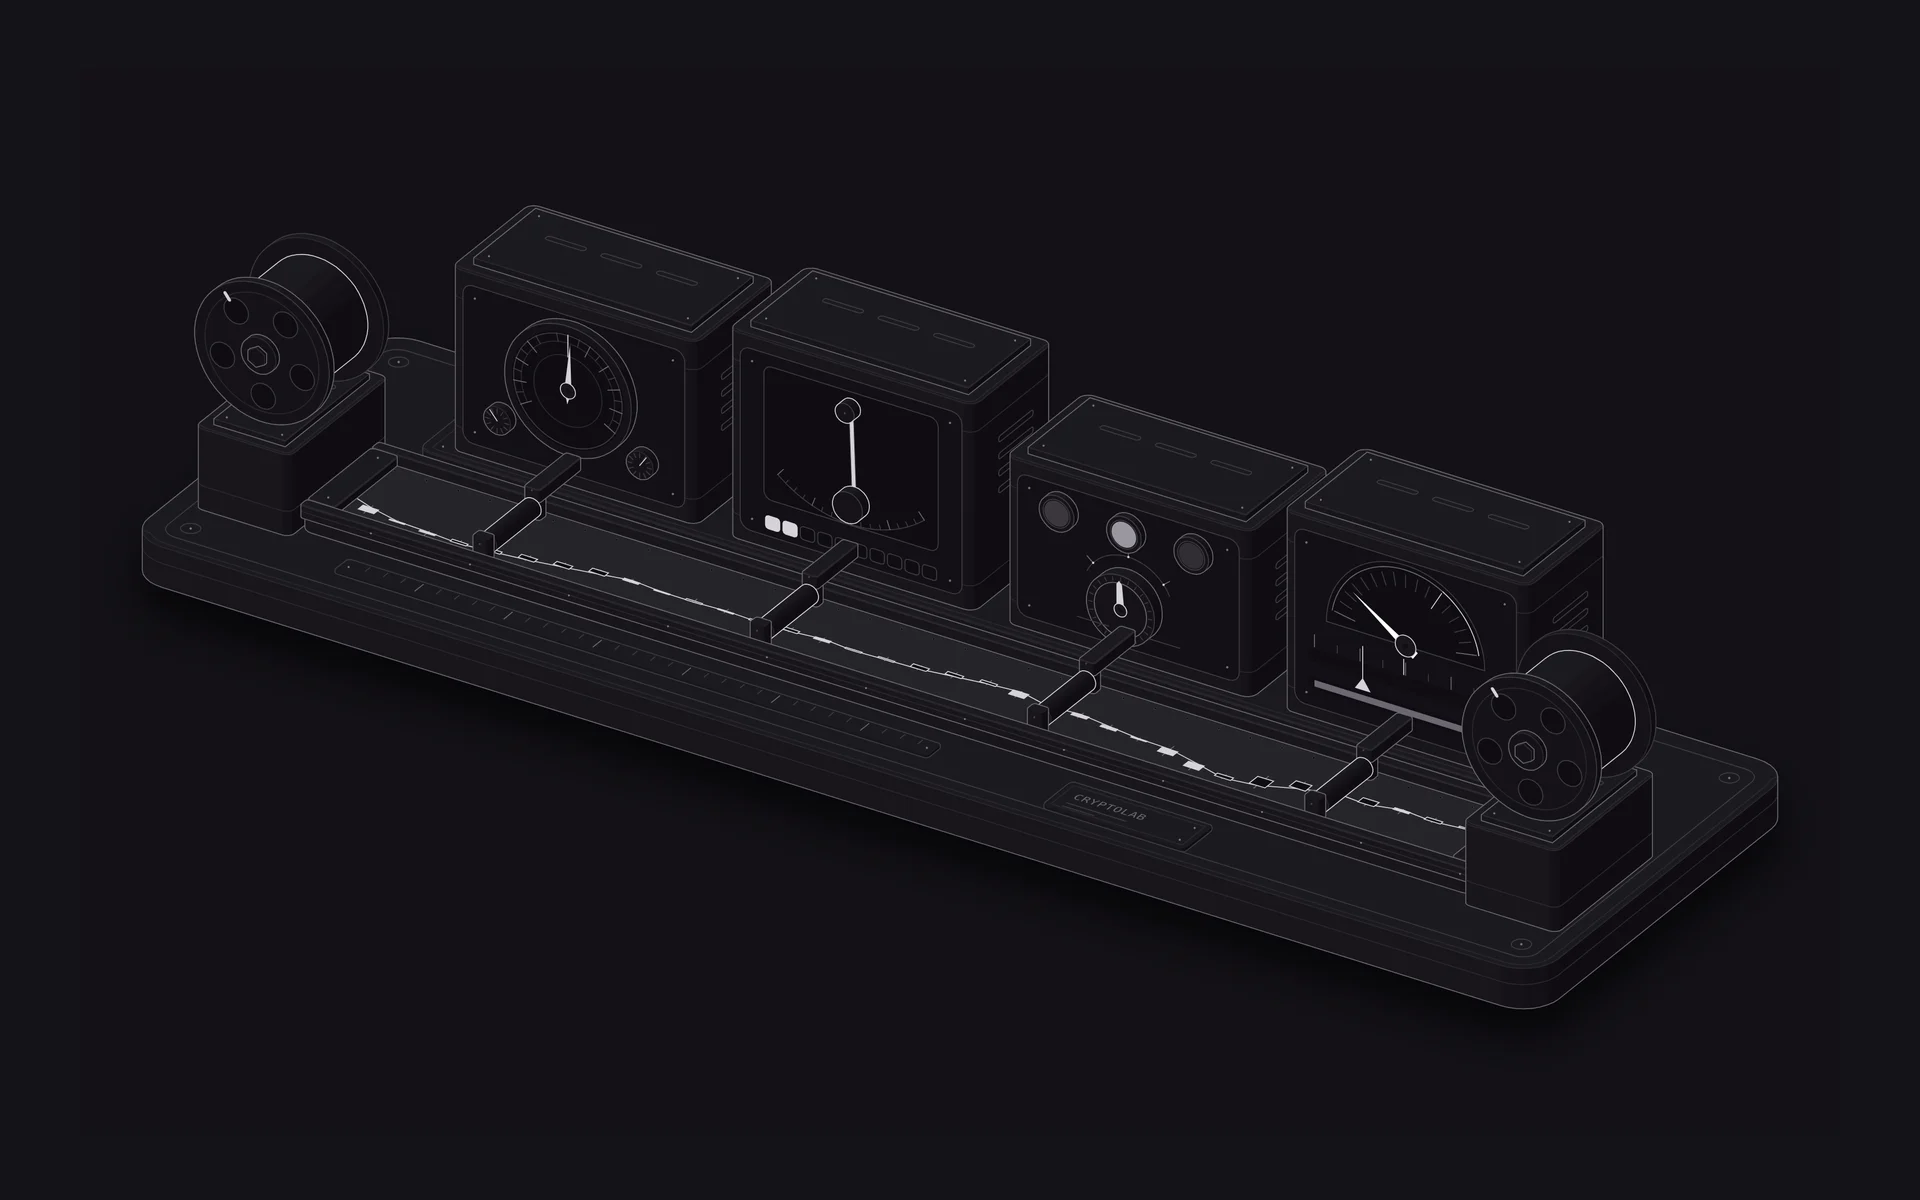
A laboratory instrument
A tape of hourly bars runs through a chain of meters: efficiency, volatility, market regime. The verdict needle rests on “no edge” until the walk-forward test proves otherwise.
Screens
Under the hood
- Python with a C++ core through pybind11.
- GJR-GARCH-t, HAR-RV, a hidden Markov model, variance-ratio and Hurst tests.
- Checks without look-ahead: walk-forward, Diebold–Mariano, purged cross-validation.
- An exchange rate limiter and an offline demo on synthetic data.
- 25 tests, including a C++ vs numpy check. Not investment advice.
Python · C++ · pybind11 · NumPy